


Bentonite CAS: 1302-78-9
A slowdown in consumer spending is reshaping demand for food ingredients, preservatives, cosmetic chemicals, and specialty products. Manufacturers must adapt to new consumption patterns and shifting market priorities.
Carve-out fever is sweeping the chemical industry as diversified firms separate specialty units to sharpen focus and unlock value. By divesting niche businesses, companies can streamline operations, fund core growth, and sharpen their chemical business strategy. The specialty chemicals market is reshaping as these carve-outs reshape supply chains and investment flows.
Polypropylene markets entered July with changing supply economics as LPG availability improves and crude prices reshape propylene production costs. Procurement teams should understand how these shifts may influence PP pricing, supplier strategies and purchasing decisions over the coming months.

Portfolio restructuring among major specialty chemical companies is creating new procurement considerations for buyers. As asset sales continue across the industry, companies should review supply agreements and strengthen supplier continuity planning for H2 2026.
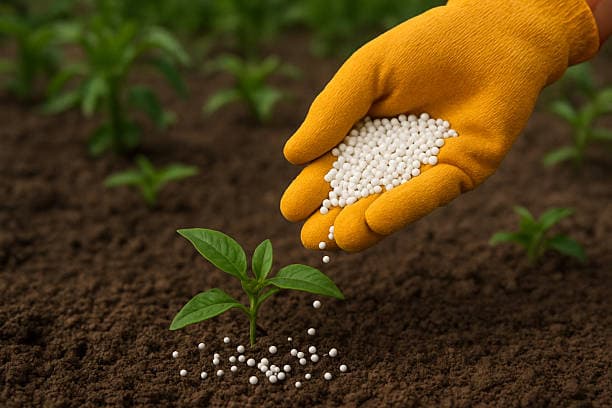
Urea prices in 2026 are poised for a rebound as Gulf exports climb back to 75% of pre‑war levels. This shift reshapes demand in the Southern Hemisphere, offering new buying windows for fertilizer importers. TradeAsia tracks the latest market dynamics for SABIC and QAFCO urea.
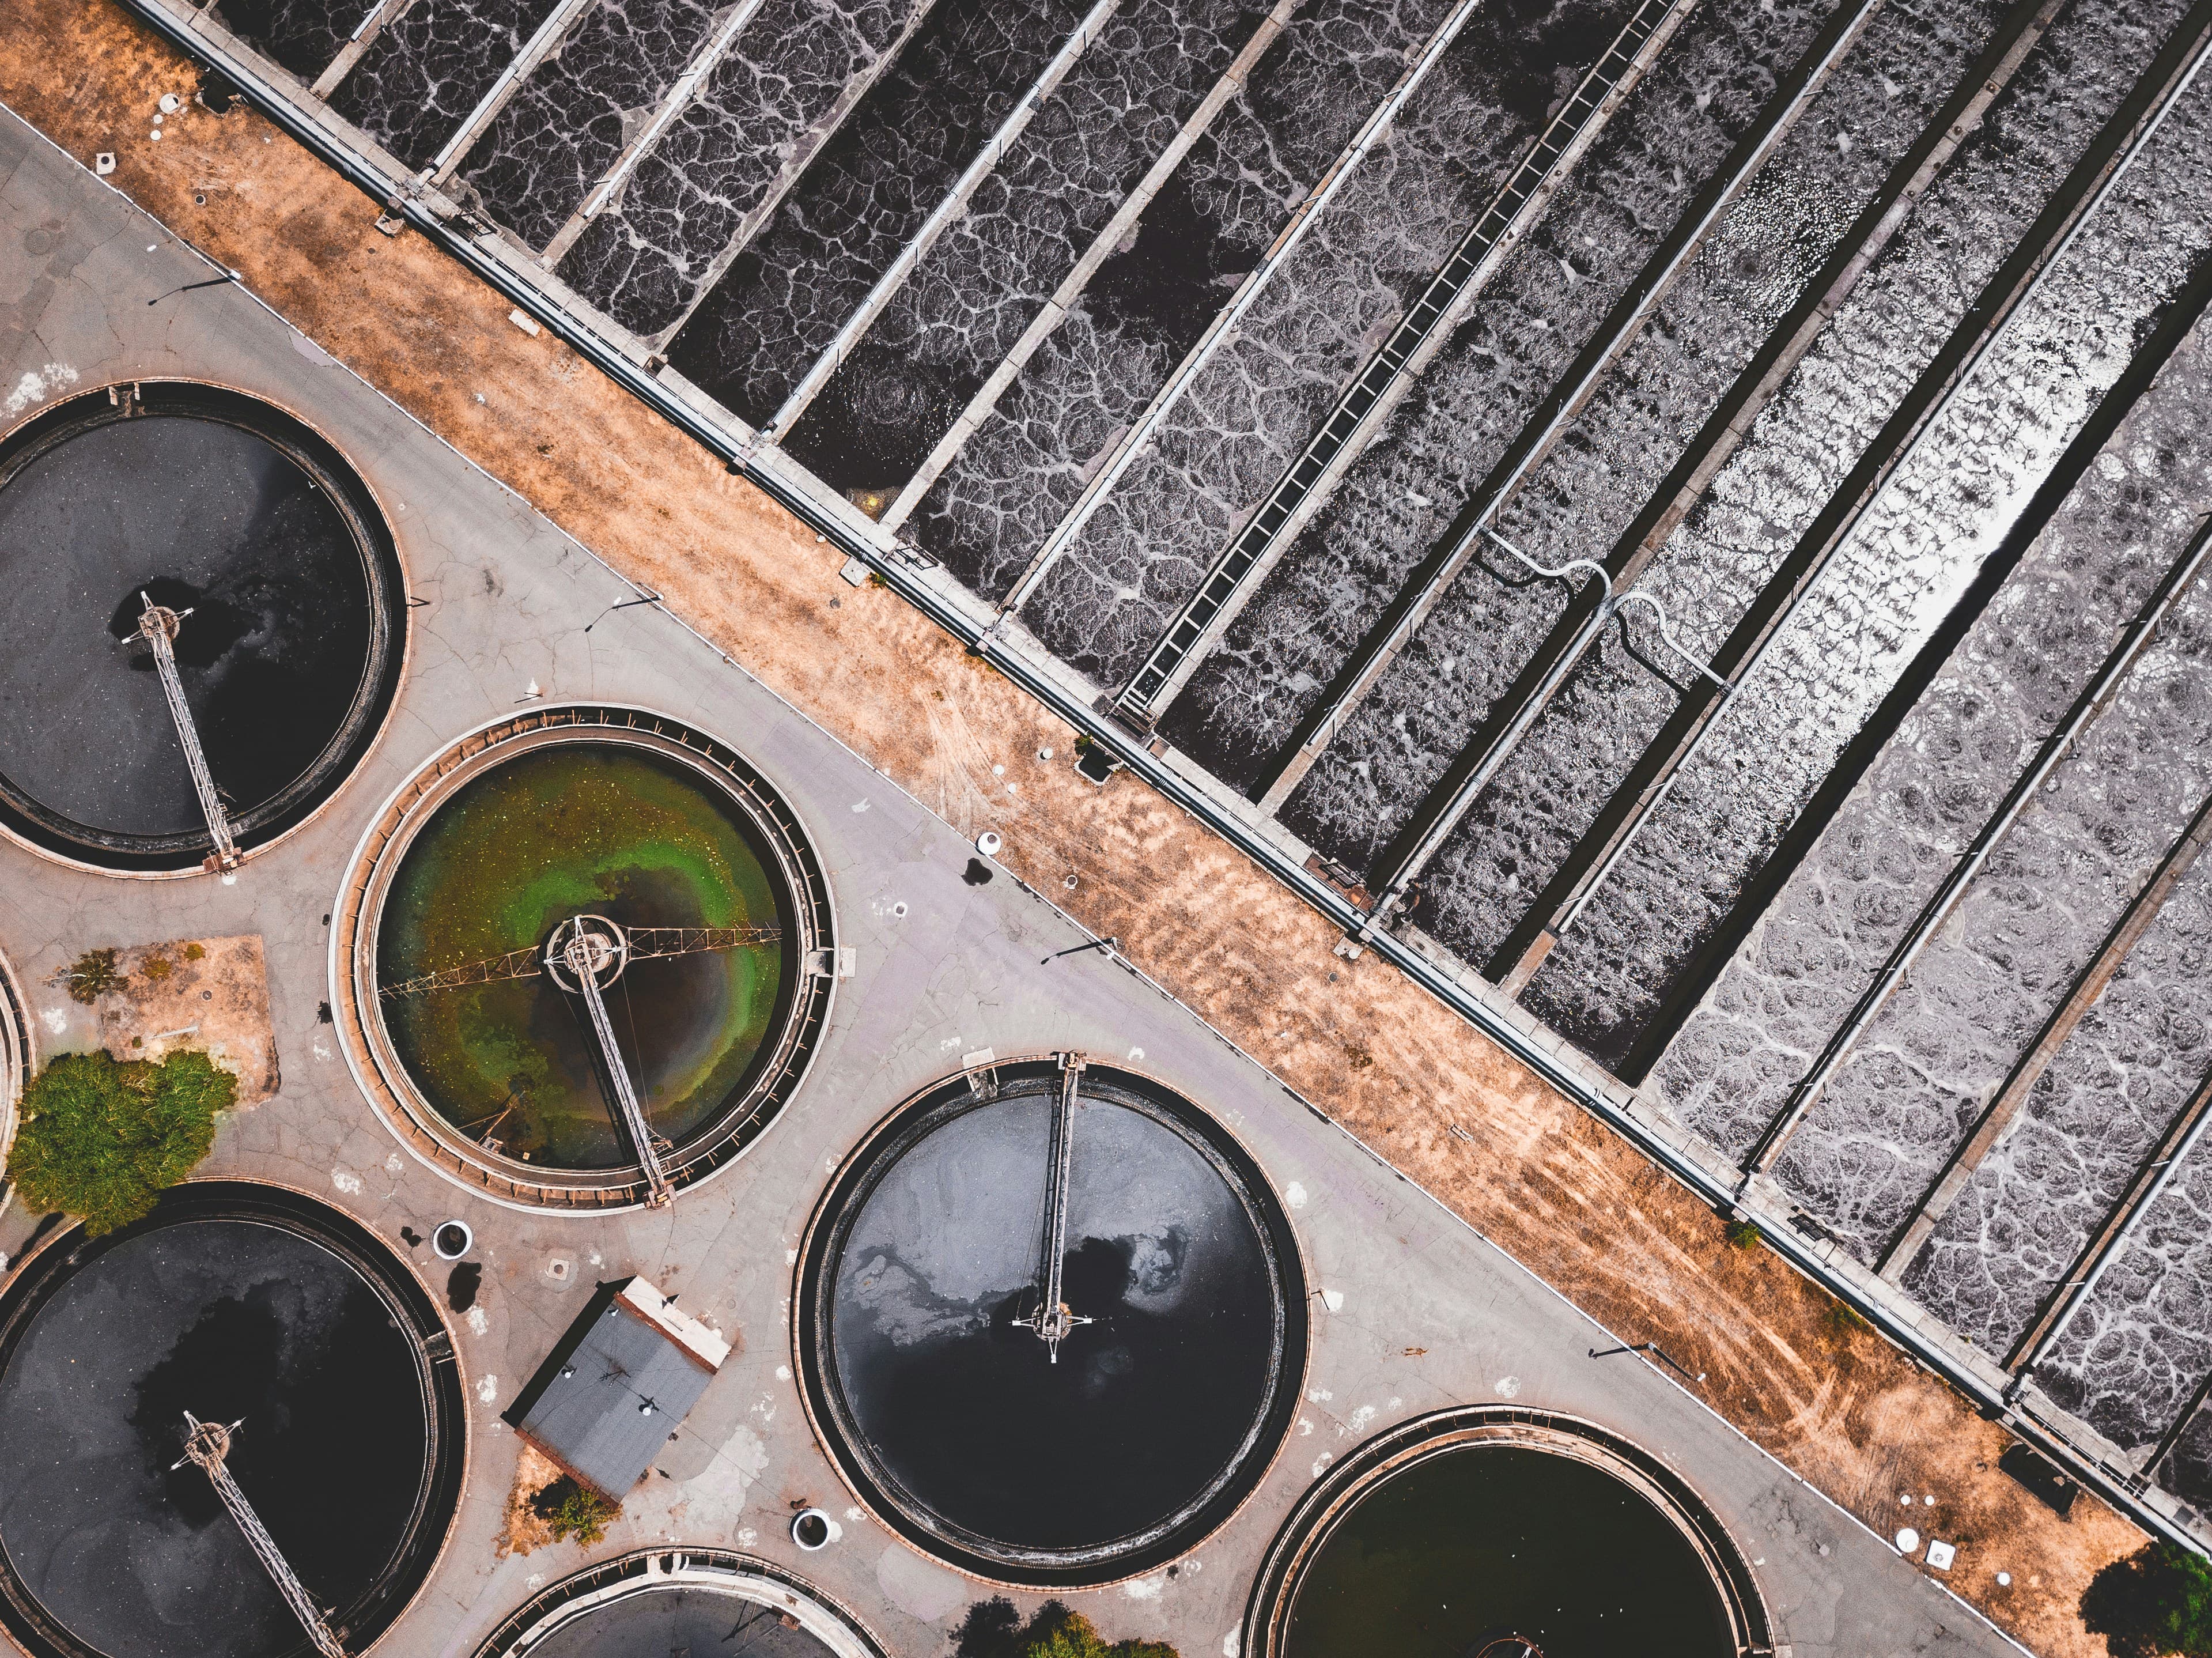
As desalination plants across the GCC return to normal operations following the Hormuz recovery, utilities are rebuilding inventories of critical water treatment chemicals. Demand for PAC, polyacrylamide, sodium hypochlorite, scale inhibitors, and biocides is surging, creating significant procurement opportunities for suppliers serving the Middle East water sector.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.